The Barrier to Demo is Dead. The Barrier to Launch Just Got Higher
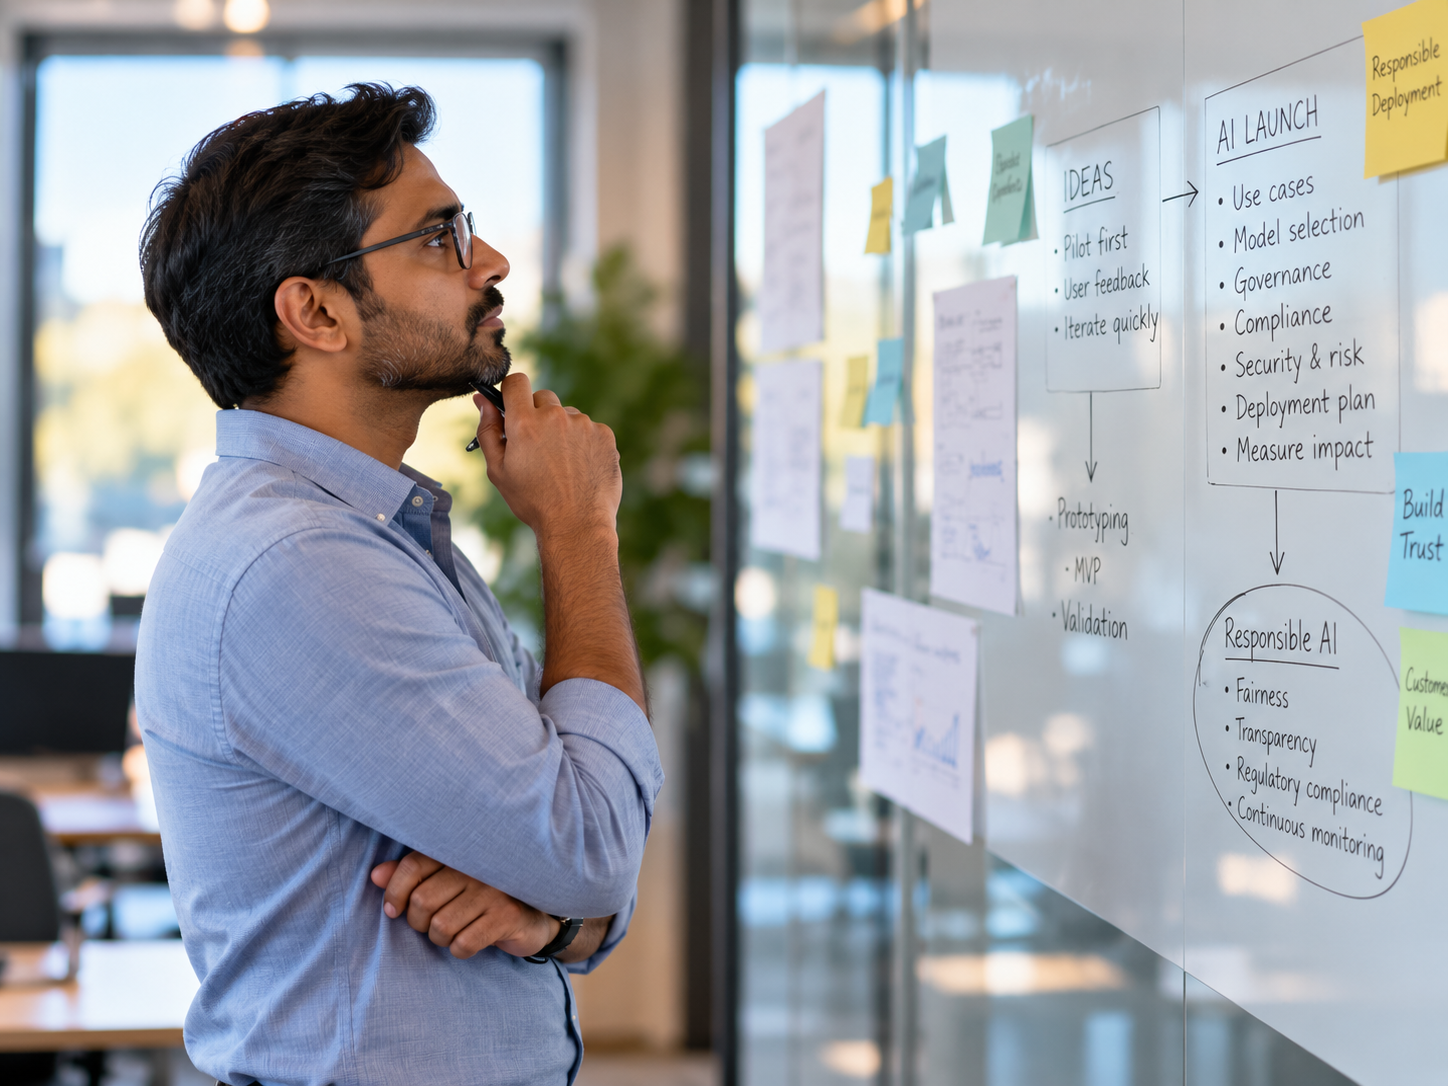
technology professional reviewing an AI deployment plan on a glass board, considering governance, compliance and responsible implementation.

Why trusted deployment, governance and operational confidence are becoming the real competitive barriers in regulated AI

Core argument: It is now easy to build something that looks convincing. It is still hard to launch something that is trusted, governed and fit for use in a regulated environment.

Not long ago, if a prospective client saw a specialist AI product and said, “We think we could build that ourselves,” it usually meant a significant investment of time, money and technical resource.

Now, it may mean a week.

In truth, it may not even take that long.

With today’s AI tooling, the barrier to creating a demo has collapsed. A capable team can build something that looks credible in hours and something reasonably impressive in days. That should not surprise anyone in 2026. In fact, if it still took months to mock up a conversational affordability journey, I would be more worried.

That is the point.

The ability to demo is no longer the test.

The real question is whether that same prototype can be launched, governed, trusted and maintained in a regulated environment. That is where the challenge now sits – and, in many ways, that barrier has become higher, not lower.

The new reality: fast to prototype, hard to operationalise

We have seen this firsthand.

A prospective client sees our product, understands the use case, and thinks: surely we can build a version of this ourselves.

Sometimes they do. Sometimes they come back months later having tried.

Usually, what they discover is that getting to 50% of the job is entirely possible. In some cases, they may even get to 70%. The prototype can ask questions, capture answers, and create the impression of a working journey.

But getting from there to something that can be launched in a live affordability process is a very different challenge.

That is because the value is not in a chatbot asking questions. It is in the full system around it – the language choices, sequencing, thresholds, prompts, validations, fallbacks, explainability, governance, monitoring and continuous optimisation that make the output usable in the real world.

Why the barrier to launch is actually getting higher

There is a misconception that because AI tools are improving quickly, the barrier to entry is disappearing everywhere.

It is disappearing for demos. It is not disappearing for deployment.

In regulated sectors especially, launch now comes with more scrutiny than before. More firms have AI working groups, AI governance forums, model oversight processes, data protection reviews and risk committees. Some have effectively paused or blocked AI adoption altogether until they are comfortable with controls.

That may slow things down, but it also reflects a genuine shift: firms know that putting AI into customer journeys is not just a product decision – it is a governance decision.

That means the bar is higher in areas such as:

  • evidencing fairness and consistency

  • handling personal data safely

  • supporting vulnerable customers appropriately

  • creating auditability and explainability

  • integrating into existing operational and compliance workflows

  • maintaining confidence after go-live, not just before it

Fast launch is valuable.

Fast launch without confidence is not.

The hidden gap between “works” and “works in production”

This is where internal builds often get underestimated.

A prototype can prove that an LLM can hold a conversation. It does not prove that the journey will perform consistently across real customers, under real stress, across edge cases, with messy language, changing portfolio needs, operational handoffs, MI requirements and regulatory expectations.

In affordability, that gap matters a lot.

A system may seem to work well in workshops or internal testing. It may perform well with colleagues, trained agents or idealised scenarios. But that is not the same as handling real consumers dealing with stress, confusion, vulnerability, incomplete information or reluctance to engage.

That is why some organisations who start with “we’ll build it” later return to buy.

Not because their team is weak.

Not because the technology is impossible.

But because moving from a promising prototype to a production-grade, trusted, maintainable capability turns out to be far more expensive and distracting than first expected.

Build cost is rarely the real cost

One of the biggest mistakes in the build vs buy discussion is treating “build cost” as if it ends at the demo.

It does not.

The real cost includes governance, optimisation, monitoring, retraining, compliance support, ongoing tuning and the internal time required to keep improving the journey as customer behaviour and regulation evolve.

There is also an opportunity cost.

Every month spent building is a month without the uplift in engagement, completion, agent efficiency or customer outcomes that a live solution could already be delivering.

That is often the piece that gets missed.

The question is not just, “Can we build it?”

It is, “What are we not doing while we try?”

The strategic question

For most firms, affordability is mission-critical.

But building affordability infrastructure is not their core differentiator.

Their edge is in brand, distribution, funding, servicing model, products, customer relationships or operational strategy. It is rarely in wanting to dedicate permanent internal resource to tuning and maintaining affordability conversation design, behavioural optimisation, regulatory evidence and model oversight.

That is why specialist focus still matters.

Not because nobody else can build a version.

But because very few want to keep investing in all the work required after version one.

That is where the real barrier now sits.

Final thought

The old moat was technical difficulty.

The new moat is trusted deployment.

So yes – the barrier to demo is dead.

That is not bad news. It is simply the new reality.

But the barrier to launch has not fallen with it. In many organisations, it has got higher.

And that is the distinction that matters.

Because in regulated AI, the demo is the easy part.

Launch is where the real work starts.
Rachel Curtis

Rachel Curtis

CEO and Founder

Rachel Curtis is CEO of Inicio AI, a specialist provider of digital income and expenditure assessment technology. Through Inicio’s work with lenders, collections organisations and debt advice providers, Rachel brings a practical perspective on the relationship between affordability assessments, operational performance and customer outcomes.

Her focus is on demonstrating how better financial understanding can deliver meaningful benefits for both organisations and their customers.
AI Affordability Assessments and Consumer Duty

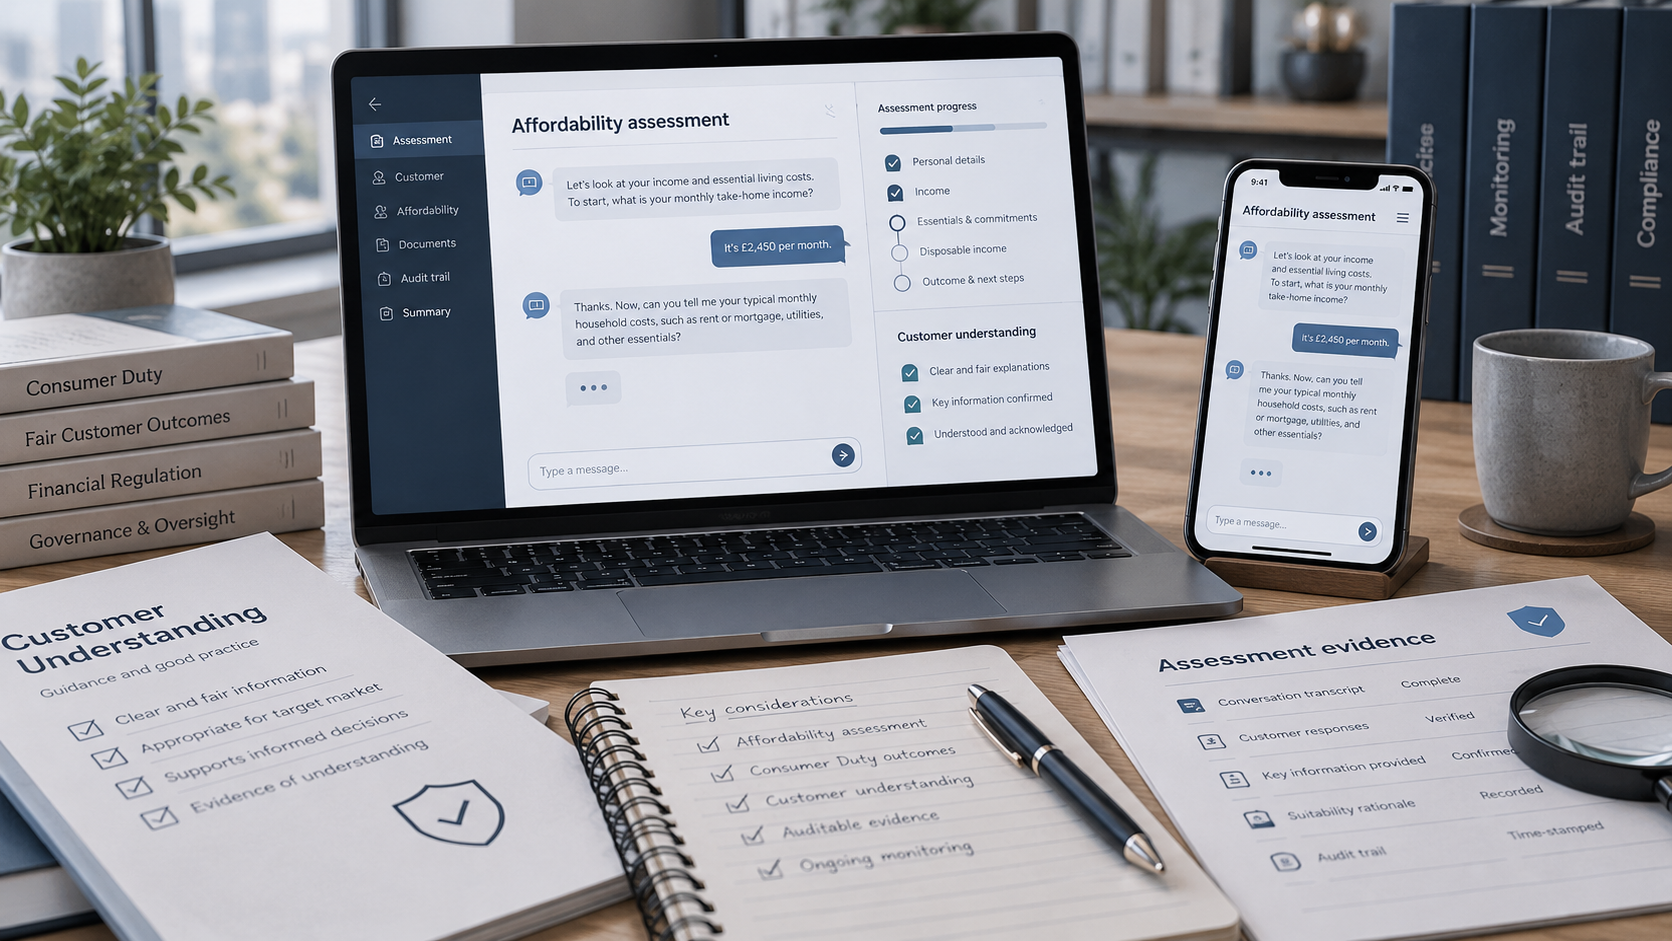
AI-powered affordability assessment displayed on digital devices, illustrating FCA Consumer Duty, customer understanding, regulatory compliance and auditable financial assessments.

The FCA has raised the bar on Consumer Duty. Discover how AI affordability assessments can help lenders evidence the Consumer Understanding outcome.

In March 2026, the Financial Conduct Authority published its review of the Consumer Understanding outcome under Consumer Duty. For lenders using AI affordability assessments, it makes for instructive reading, not because it introduces new rules, but because it describes, in practical terms, what good actually looks like, and where many firms are falling short.

The shift: from communication to evidence

The central message is clear. Firms are not being asked simply to provide information, they are expected to demonstrate that customers:

  • understand what they are being told
  • can act on it
  • and are supported at the right moments in their journey

This is a meaningful shift. The FCA explicitly challenges reliance on:

  • the absence of complaints
  • sales outcomes
  • or assumptions that “clear wording” equals understanding

Instead, firms are expected to build evidence-based, testable, and auditable approaches to communication, supported by management information, testing, and governance.

Where firms are falling short

The review identifies consistent patterns across firms:

  • Reactive rather than proactive approaches to vulnerability
  • Testing that is one-off, superficial, or poorly evidenced
  • Limited ability to show how insight leads to change
  • Governance that focuses on compliance metrics rather than comprehension

These are not edge cases. They are recurring themes and at the same time, the FCA is equally clear on what good looks like.

What good looks like in practice

Firms performing well are doing a number of things differently:

  • Identifying vulnerability early and at key moments of stress
  • Capturing accessibility needs once and applying them consistently
  • Testing communications with real customers, before and after changes
  • Using tools and journeys that actively support understanding
  • Producing management information that evidences comprehension, not just activity

In one example, a firm set an internal benchmark that at least 80% of customers must correctly recall key information and iterated its communications until that standard was met. This is the level of rigour the FCA is pointing towards.

Why this matters most in affordability

For lenders, these expectations land most clearly in affordability and income & expenditure assessments. These are the moments where:

  • customers disclose sensitive financial information
  • vulnerability is most likely to surface
  • understanding is critical to outcomes

And they are also the moments that will be most heavily scrutinised if something goes wrong. The question is no longer “Did we ask the right questions?” it’s “Can we evidence that the customer understood, and that we responded appropriately?”

A structural challenge for many firms

Traditional affordability processes were not designed with this standard in mind. They are often:

  • agent-led and variable
  • difficult to evidence consistently
  • reliant on interpretation rather than structure
  • weak in producing auditable insight

Even where technology is introduced, many solutions still sit outside the regulatory perimeter, acting as tools rather than accountable processes. That distinction is becoming more important. For firms looking to meet their AI affordability assessments Consumer Duty obligations, that distinction is now critical.

How AI affordability assessments embed regulation into the process

In a market where AI affordability assessments and Consumer Duty compliance are scrutinised, Inicio operates within the regulatory perimeter, not outside it. Inicio is an FCA-regulated provider of affordability assessments, using conversational AI to capture income, expenditure and vulnerability in a structured, consistent and auditable way. This changes the role of technology. Rather than supporting the process, it becomes the process, one that is:

  • consistent across every interaction
  • adaptable in real time to customer responses
  • designed to support understanding, not just data capture
  • capable of producing structured, timestamped evidence of customer outcomes

Every interaction generates management information that can be fed directly into governance, aligned with the FCA’s expectation that firms move towards comprehension-driven insight, not just compliance reporting.

From aspiration to evidence

The FCA’s review is not a warning shot. It is a roadmap and sets out clearly:

  • what firms should be doing
  • how they should be measuring it
  • and the level of evidence expected

For lenders, this raises a fundamental question: Is your affordability process designed to meet that standard or to evidence it? Because increasingly, those are not the same thing.

The direction of travel

Consumer Duty is pushing the industry beyond communication and into accountability.

Understanding is no longer assumed, it must be demonstrated and that requires processes that are structured, testable and capable of standing up to scrutiny.

Final thought

Affordability assessments are among the highest-stakes interactions in the customer journey, they are where:

  • vulnerability must be identified
  • understanding must be clear
  • and decisions must be defensible

As expectations continue to rise, the firms that succeed will not be those that say the right things but those that can prove them.

Caroline Walton

Caroline Walton

Strategic Advisor

A former CEO and experienced Non-Executive Director, Caroline has first-hand experience of navigating complex regulatory challenges, working with the FCA and balancing commercial performance with fair customer outcomes.

She has a particular interest in how AI and emerging technologies can transform financial services, strengthen governance and improve customer experiences.

Caroline is passionate about responsible innovation, believing that regulatory compliance and commercial success should reinforce one another, rather than compete.

Inicio March 2026 Newsletter

Read our roundup of everything in the first quarter of 2026 for Inicio, with a showcase on BNP Paribas Personal Finance and a brand new sector for us once again.

We have noticed that AI continues to attract much attention, is it right or is it worrying for the workplace and regulated sectors?  Read about the regularly three myths we hear and why they are worth challenging.


New Client Announcement – Finclusion

New motor finance lender adopts conversational AI affordability technology at origination, setting a new standard for responsible lending

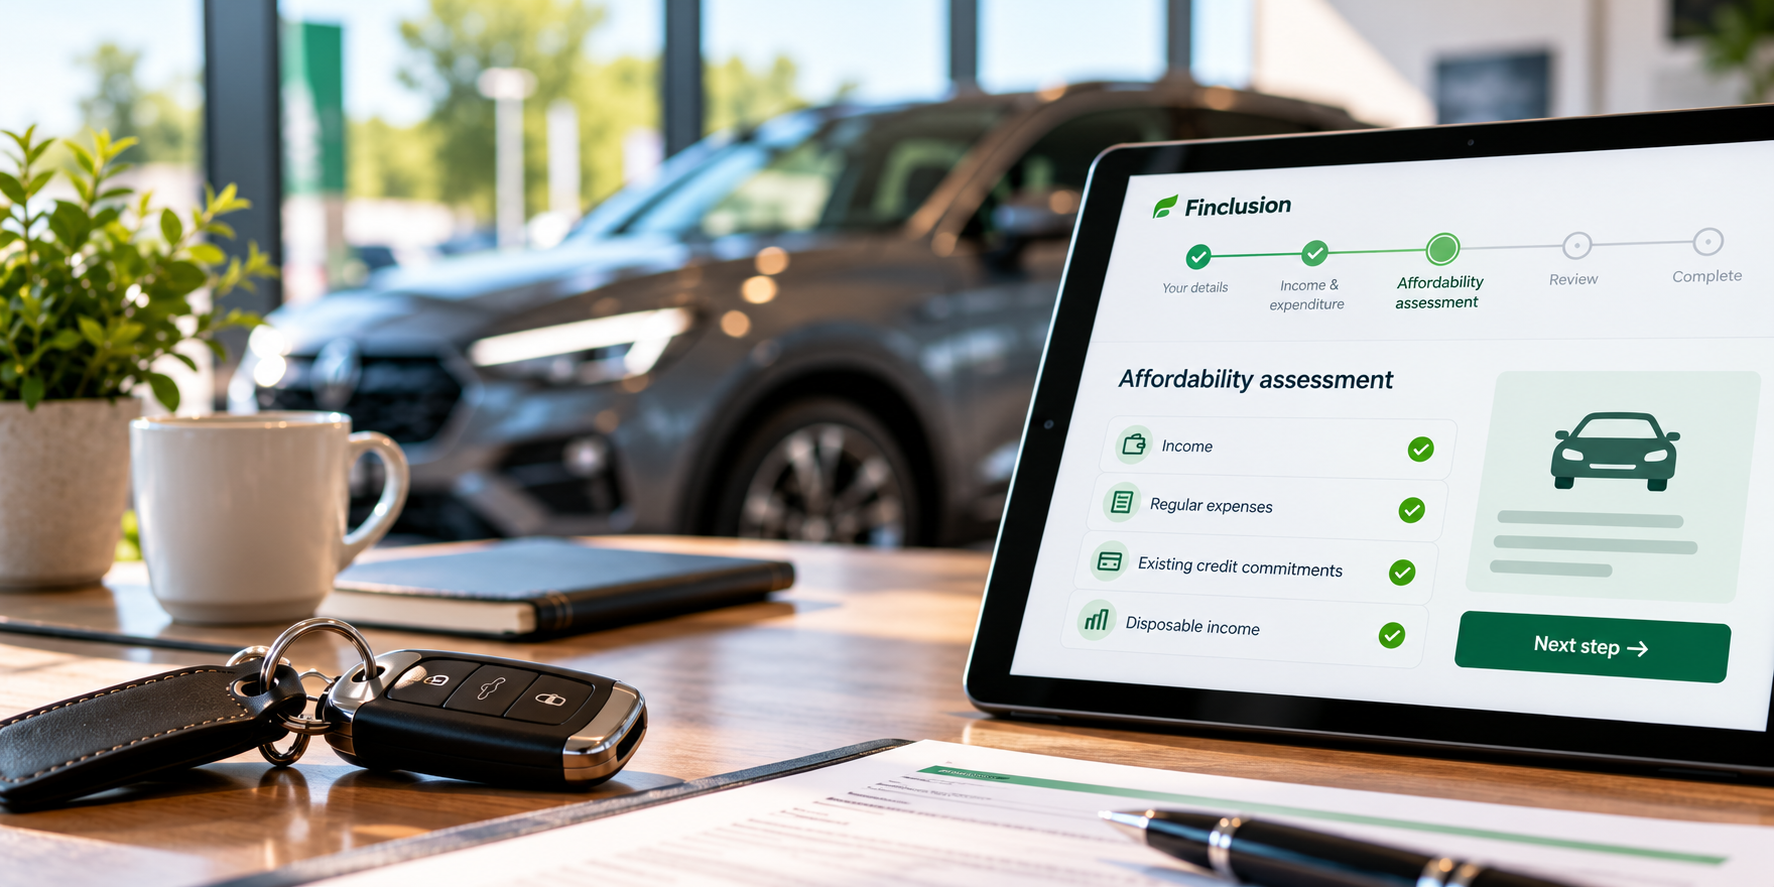
Finclusion, a new entrant to the UK motor finance market, has partnered with Inicio AI, creators of a virtual agent, Budgie, trained to help customers complete a detailed affordability assessment in a conversational manner at the very start of the customer journey. 

This marks an important step forward for the motor finance sector, where affordability assessments have traditionally relied heavily on indirect indicators such as credit data and scorecards.

By introducing a conversational AI affordability assessment at origination, Finclusion is establishing a model designed to deliver greater transparency, deeper financial understanding, and improved customer outcomes from the outset. 

Inicio AI technology enables lenders to engage customers in structured, explainable conversations about their financial circumstances, providing a clearer and more complete picture of affordability to support responsible lending decisions.

While Inicio’s platform has been widely adopted to support customers experiencing financial difficulty, Finclusion’s implementation represents a significant evolution, using conversational affordability proactively, before lending decisions are made.

Chris Bosworth – CEO of Finclusion, said:
“As a new lender, we have the opportunity to design our customer journey around responsible lending from day one. Partnering with Inicio AI allows us to embed affordability at the very start of that journey, ensuring we build a clear and transparent understanding of each customer’s financial position. This is fundamental to our commitment to delivering sustainable outcomes and building long-term trust with our customers.”

 The partnership comes at a pivotal time for the motor finance sector, as lenders face increasing focus on affordability assessments and customer outcomes.

 By embedding affordability assessments into its origination process, Finclusion is helping to establish a forward-looking approach aligned with evolving regulatory expectations and best practice.

 Rachel Curtis, CEO of Inicio, said:
“We are proud to support Finclusion in embedding affordability at the earliest stage of the lending journey. This represents an important shift in how affordability is approached within motor finance, moving from a reactive exercise to a proactive foundation. Finclusion’s approach demonstrates how lenders can use technology to strengthen responsible lending and deliver better outcomes for customers.”

 This partnership reflects a shared commitment between Finclusion and Inicio to improve how affordability is understood and assessed across the lending lifecycle.

 As the motor finance sector continues to evolve, initiatives such as this demonstrate how lenders can combine technology and intent to establish new standards in responsible lending.

 Rupert Lyle, Fund Principal of West Midlands Co-Investment Fund from Future Planet Capital Regional, said: 

“Future Planet Capital Regional is delighted to support the combination of Finclusion and Inicio. It brings together two businesses focused on using technology to better understand customers and embed responsible lending from the very start of the journey. As scrutiny around affordability continues to grow, approaches like this — combining transparency, technology and intent — have the potential to set a higher standard for the sector.” 

Setting a New Standard in Motor Finance

Affordability Assessment in the Motor Finance Sector

Finclusion Introduces Innovative Assessments at the Start of the Customer Journey

The UK motor finance sector is undergoing one of the most significant periods of reflection and change in its history. For lenders, the question of how AI affordability assessments can support responsible lending in motor finance has never been more pressing.

In recent years, questions around affordability, transparency, and customer outcomes have moved sharply into focus. Large-scale redress schemes and increased regulatory scrutiny have highlighted the need for lenders to demonstrate not only compliance, but genuine understanding of a customer’s ability to sustain borrowing.

This moment is not just about addressing the past. It is about shaping the future.

Against this backdrop, a new generation of lenders is emerging, organisations building their models around responsible lending from the outset, rather than adapting retrospectively. Finclusion is one such lender, using AI affordability assessments in motor finance.

Designing affordability in from day one

As a new entrant to the motor finance market, Finclusion has made a deliberate decision to embed affordability assessments at the very start of the customer journey, working in partnership with Inicio AI.

This marks a significant departure from traditional approaches, where affordability assessments have often relied heavily on only indirect data sources such as credit files, scorecards, and income estimates.

Finclusion is introducing conversational affordability assessments creating an additional transparent and structured way to understand a customer’s financial position before lending decisions are finalised.

This allows affordability to be assessed not simply as a compliance checkpoint, but as a meaningful part of responsible lending.

Moving affordability upstream

Inicio’s conversational AI platform has historically been deployed to support customers during periods of financial difficulty, helping lenders engage sensitively, understand individual circumstances, and agree sustainable outcomes.

Finclusion’s implementation represents a new and important evolution.

By introducing Inicio’s affordability solution at origination, Finclusion is proactively building deeper financial understanding into the lending process itself. 

This shift moves affordability from a reactive exercise to a proactive foundation.

It reflects a belief that better conversations at the start of the journey can lead to better outcomes throughout the life of the agreement.

Setting a new tone for motor finance

As regulatory expectations continue to evolve, AI affordability assessments in motor finance are becoming a critical tool for lenders needing to demonstrate not only that affordability has been assessed, but that it has been assessed appropriately.

Finclusion’s approach reflects a forward-looking perspective, recognising that responsible lending is not just about meeting regulatory requirements, but about building sustainable relationships with customers.

By embedding conversational affordability from the outset, Finclusion is helping to establish a model built on clarity, understanding, and transparency.

A shared commitment to better outcomes

Inicio is proud to support Finclusion in this important step.

This partnership reflects a shared commitment to improving how affordability is understood and assessed, ensuring customers are supported appropriately from the very beginning of their journey.

As the motor finance sector continues to evolve, initiatives like this demonstrate how technology and lender intent can work together to set new standards for responsible lending.

Victoria Oliver

Victoria Oliver

Chief Commercial Officer

Victoria Oliver is Chief Commercial Officer at Inicio AI, working with organisations across financial services, collections and debt advice to explore how digital income and expenditure assessments can improve operational efficiency and customer experience.

Her commercial perspective focuses on helping organisations evaluate technology that supports their operational objectives while delivering meaningful improvements for customers and frontline teams.