If Your I&E Assessment Makes No Difference to Collections, You’re Doing It Wrong
Woman reviewing her Income and Expenditure Form

The industry has spent years treating income and expenditure assessments as a compliance exercise. But what if that thinking is costing creditors millions in missed collections?

I’ve heard a claim repeated across the debt collection industry that income and expenditure (I&E) assessments make little or no difference to collections outcomes.

And here’s the thing. I don’t entirely disagree.

But I think there are a few important words missing.

A poor-quality I&E makes little or no difference to collections outcomes.

And that’s a very different argument.

Why have income and expenditure assessments become a tick-box exercise?

Somewhere along the way, parts of our industry started treating the I&E as something that simply needs to be completed. A regulatory requirement. A box to tick. A process to get through before agreeing a repayment arrangement.

And once you view an I&E that way, the commercial logic seems obvious.

Why spend more than you need to? Find the cheapest provider, collect the information, demonstrate compliance and move on.

Except that approach misses the fundamental point of an I&E.

The purpose isn’t simply to collect financial information. It’s to understand a customer’s true financial circumstances and establish an affordable, sustainable repayment arrangement.

And the quality of that understanding has a direct impact on the outcome.

What's the difference between collecting financial information and understanding it?

Consider a customer who tells you their household expenditure is £1,000 a month.

A basic I&E might capture that figure, calculate disposable income and move on.

But what happens when you explore the detail?

In one real example, when we helped a customer break down their household expenditure into individual categories, the actual total came to just over £900.

That’s nearly £100 a month of additional disposable income that might otherwise have gone unidentified.

Not because the customer was deliberately providing inaccurate information, but because estimating expenditure and understanding exactly where your money goes are two very different things.

And sometimes the difference is much smaller.

An additional £10 a month might not sound transformational. But across a portfolio of tens of thousands of customers, £10 a month in additional sustainable repayments can represent millions of pounds in potential collections over time.

Small improvements in affordability accuracy can create substantial commercial value at scale.

Of course, the reverse is equally important.

A detailed, properly checked I&E may reveal that a customer can afford less than initially indicated.

That’s not a failure. That’s a better outcome.

Because an arrangement that looks good on day one but breaks down two months later isn’t good for the creditor or the customer.

Can better affordability assessments improve both payment values and stick rates?

There’s an assumption that increasing repayment values must come at the expense of sustainability.

Our experience suggests otherwise.

At Inicio AI, we’re now live with more than 20 clients across multiple sectors, consistently demonstrating the value of more detailed, intelligent affordability assessments.

For example:

  • BPO Collections achieved a 60% increase in payment values alongside a 5% improvement in stick rate.

  • A banking client achieved a 4% improvement in stick rate.

  • Across our client base, we’re consistently seeing improvements in payment values.

These results matter because they challenge the assumption that an I&E has little bearing on collections performance.

The opportunity isn’t simply to get customers to pay more.

It’s to help customers understand what they can genuinely afford, so that where higher payments are appropriate, they’re also sustainable.

Does a more detailed I&E assessment mean more time and more customer drop-off?

It’s a fair challenge.

Historically, collecting a detailed I&E could mean a lengthy conversation with an agent, significant operational cost and a risk that customers disengage before completing the process.

But technology has changed what’s possible.

Our conversational AI solution, Budgie, typically enables customers to complete a detailed affordability assessment in 10–15 minutes, with completion rates approaching 90%.

And importantly, this isn’t simply a digital form.

Budgie engages customers in a conversation, gathering detailed financial information, checking responses, identifying inconsistencies and appropriately challenging information where clarification is needed.

That distinction matters.

A short form might be quicker to build and cheaper to provide. But if it produces less accurate information, how much value is it really delivering?

How can I&E assessments help customers understand their finances?

There’s another benefit we don’t talk about enough.

For many people experiencing financial difficulty, completing a detailed I&E can be the first time they’ve properly understood their own finances.

Breaking down expenditure into individual categories can highlight spending patterns they hadn’t recognised.

Perhaps they’re spending more on takeaways than they realised. Perhaps they’ve underestimated essential household costs. Perhaps there are expenses they’ve simply forgotten.

The point isn’t to tell customers how to spend their money.

It’s to give them greater visibility and control over their finances.

That awareness can influence future behaviour, improve financial resilience and help customers maintain affordable repayment arrangements.

A good I&E doesn’t just measure affordability. It can help customers understand and manage it.

That’s a meaningful customer outcome, not just a collections benefit.

Why could the cheapest I&E solution be your most expensive decision?

Here’s where I think the industry needs to fundamentally rethink its approach.

Too often, we evaluate I&E solutions based on their cost per assessment.

But surely the more important question is: what value does each assessment generate?

If a more effective I&E identifies just £10 a month in additional sustainable repayments, what does that mean across your portfolio?

And what is the value of fewer broken arrangements, fewer repeat contacts, less collections activity and reduced operational cost?

For our clients, the combined impact of improved payment values, better stick rates and operational efficiencies is delivering returns of 10x or more on their investment.

Suddenly, the price of completing the I&E looks like a rather small part of the equation.

We’re an FCA-authorised business, and we understand that affordability assessments must put fair customer outcomes at their heart.

But regulatory compliance and commercial performance aren’t competing objectives.

When affordability is assessed properly, they can reinforce each other.

So, does an I&E improve collections performance?

It depends entirely on the quality of the I&E.

If you’re simply recording what a customer tells you, with little exploration, validation or challenge, then perhaps the sceptics have a point.

But if you’re gathering detailed information, helping customers understand their finances and establishing a more accurate picture of what they can sustainably afford, the evidence tells a very different story.

The question isn’t whether an I&E improves collections. It’s whether yours does.

Because a poor-quality I&E might satisfy a process. A high-quality I&E can transform an outcome.

And if you’re still buying I&Es on price alone, you might be saving pennies while leaving pounds uncollected.
Rachel Curtis

Rachel Curtis

CEO & Founder

Rachel Curtis is CEO of Inicio AI, a specialist provider of digital income and expenditure assessment technology. Through Inicio’s work with lenders, collections organisations and debt advice providers, Rachel brings a practical perspective on the relationship between affordability assessments, operational performance and customer outcomes.

Her focus is on demonstrating how better financial understanding can deliver meaningful benefits for both organisations and their customers.
What to look for in Income and Expenditure (I&E) Assessment Software

Writing Professional explaining income and expenditure assessment software to a colleague, using a laptop displaying financial dashboards and performance data.

Understanding a customer’s financial circumstances is fundamental to making informed, responsible decisions about affordability and financial support.

For lenders, collections teams and debt advice organisations, income and expenditure (I&E) assessments are an essential part of that process. But the quality of an assessment depends on more than simply collecting financial information.

The right technology can improve accuracy, reduce administrative effort and create a better experience for customers and agents alike.

So, what should organisations consider when choosing I&E assessment software?

What is I&E assessment software?

Income and expenditure assessment software is technology that helps organisations collect, organise and evaluate information about a customer’s income, essential expenditure and financial commitments.

It’s commonly used in lending, collections and debt advice to develop a clearer picture of an individual’s financial circumstances and support discussions about affordability.

Modern digital I&E solutions can offer customers the flexibility to complete assessments independently, while also supporting agents who undertake assessments through conversations with customers.

The objective is not simply to digitise a traditional form, but to make the assessment process more accessible, consistent and effective.

What makes good I&E assessment software?

Good I&E assessment software should balance accuracy, accessibility, flexibility and operational efficiency.

Accuracy and consistency

Reliable assessments depend on capturing relevant financial information in a structured and consistent way. Clear categories, appropriate prompts and opportunities to clarify unusual or incomplete responses help improve the quality of information collected.

Accessibility and flexibility

Not every customer has the same needs or preferences. Some will welcome the convenience and privacy of digital self-service, while others may prefer to speak directly with an agent.

Effective software should accommodate different customer journeys without compromising the quality of the assessment.

Integration and efficiency

Technology should simplify existing processes, not introduce additional complexity. The ability to integrate with operational systems, reduce duplicated information and minimise unnecessary administration can improve both productivity and customer experience.

Support for informed decisions

Ultimately, the value of an I&E assessment lies in how effectively the information supports understanding, decision-making and appropriate customer outcomes.

Why does digital self-serve matter?

Digital self-service gives customers greater flexibility and control over how and when they share their financial information.

Discussing personal finances can be uncomfortable, particularly for individuals experiencing financial difficulty. Providing the option to complete an assessment independently, in a familiar environment and at a convenient time, may help reduce some of those barriers.

For organisations, digital assessments can also reduce the administrative time associated with collecting financial information, allowing agents to concentrate on conversations where additional support is needed.

However, self-service should complement rather than replace human interaction.

The most effective approach recognises that customers have different circumstances, capabilities and support needs. Offering both digital and agent-supported assessments helps organisations provide an appropriate experience for a wider range of customers.

How does I&E software support Consumer Duty?

The FCA’s Consumer Duty places an emphasis on firms delivering good outcomes for retail customers, including appropriate support and the avoidance of foreseeable harm.

Accurate and accessible financial assessments can contribute to how firms meet these expectations.

Well-designed I&E software can help organisations:

  • Gather relevant financial information consistently.

  • Identify circumstances that may warrant additional support or further discussion.

  • Provide accessible assessment journeys for different customer needs.

  • Maintain clear records to support oversight and decision-making.

  • Monitor assessment processes and evaluate customer outcomes.

Importantly, technology alone cannot ensure regulatory compliance.

Firms must consider how assessment information is interpreted, how decisions are made and whether the resulting actions are appropriate for individual customers.

The value of assessment technology lies in supporting these responsibilities through better information, more consistent processes and improved visibility.

How should organisations measure success?

Assessment completion rates and processing times are useful measures of operational performance, but they don’t tell the whole story.

Organisations should also consider the quality of information collected and whether assessments lead to better-informed decisions.

Relevant performance indicators might include:

  • Assessment completion and engagement: Are customers able and willing to complete the process?
  • Information quality: Are assessments sufficiently accurate, complete and consistent?
  • Customer experience: Is the process accessible, understandable and appropriate for different customer needs?
  • Agent efficiency: Does the technology reduce administrative effort and free up time for more valuable conversations?
  • Customer outcomes: Does the information gathered help organisations identify appropriate and sustainable next steps?

By considering these measures together, organisations can build a more meaningful picture of the value their technology delivers. See our case studies for examples of success measures.

Better assessments, better understanding

Income and expenditure assessments should be more than a regulatory or operational requirement.

Done well, they create an opportunity to understand customers’ financial circumstances more accurately, support constructive conversations and make better-informed decisions.

At Inicio AI, we believe technology should make that process easier for customers and more effective for the organisations supporting them.

By combining digital self-service, structured assessment journeys and agent support, organisations can improve efficiency without losing sight of what matters most: understanding the individual behind the numbers.

Discover how Inicio AI supports digital income and expenditure assessments and helps organisations improve customer and agent experiences.

Victoria Oliver

Victoria Oliver

Chief Commercial Officer

Victoria Oliver is Chief Commercial Officer at Inicio AI, working with organisations across financial services, collections and debt advice to explore how digital income and expenditure assessments can improve operational efficiency and customer experience.

Her commercial perspective focuses on helping organisations evaluate technology that supports their operational objectives while delivering meaningful improvements for customers and frontline teams.

New Client Announcement – High Court Enforcement Group

Another great client announcement for Inicio AI and a huge thank you to all of the team, on both sides, as they go live with our affordability assessment using conversational AI.

Our new client has been working in their sector for 35 years, supporting individuals with unparalleled professional integrity and an ethical approach

We are incredibly proud to announce High Court Enforcement Group as our latest client.


New Client Announcement – Citizens Advice in North & West Kent

We are pleased to announce another new client for Inicio AI.

We’re working with North & West Kent Citizens Advice and Kent Law Centre, an organisation that gives people the knowledge and confidence they need to find their way forward, whatever their circumstances and whatever challenges they may be facing.

We are delighted to be supporting the team with our unique affordability assessment using conversational AI that guides users naturally through the assessment process, with bespoke configuration and deployment.

Built specifically for affordability assessments and refined through thousands of real customer conversations, Inicio AI gives organisations the confidence to deploy AI safely, responsibly, and at scale.

We’re excited to be working with the team and look forward to supporting their important work. 👏

How AI Makes Human Conversations More Valuable

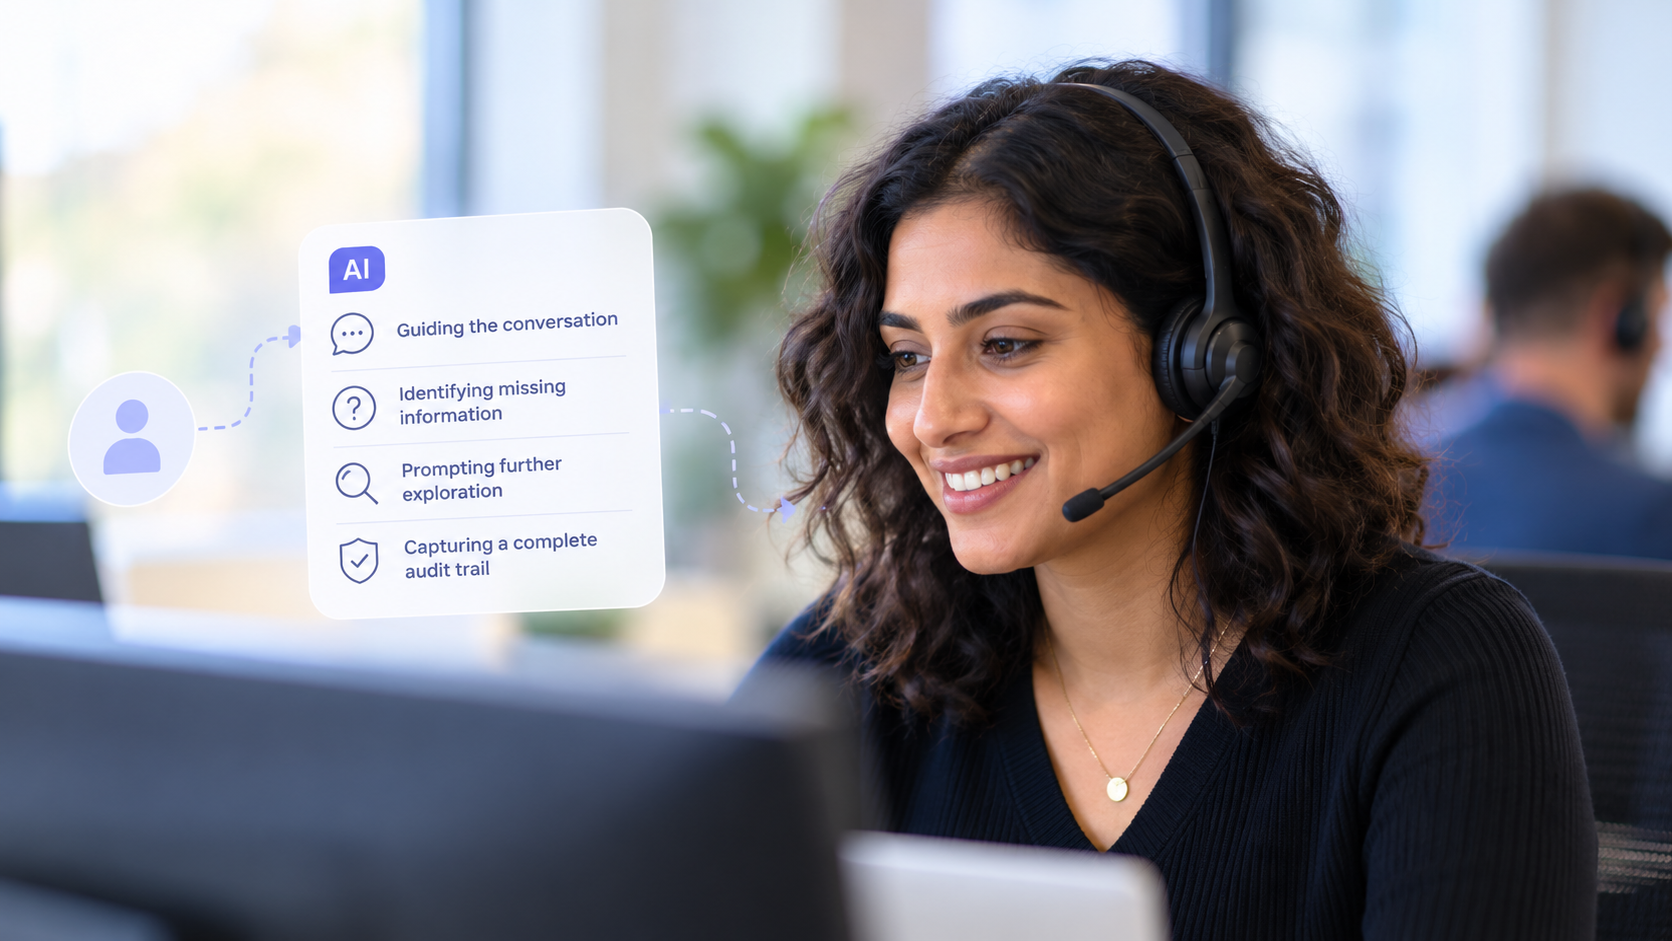
agent being guided on a customer call using AI

For years, organisations have invested in digital channels to make customer journeys faster and more efficient. Today, conversational AI is accelerating that shift even further.

Routine interactions are increasingly handled through self-service. Customers can complete straightforward tasks without speaking to an agent, often more quickly and conveniently than ever before.

But this creates an interesting consequence.

The conversations that still reach an agent are no longer the simple ones. They are the conversations where customers need reassurance, where circumstances are more complex, and where professional judgement really matters.

The better self-service becomes, the more valuable the human agent becomes.

AI Should Make Agents Exceptional

Much of today’s AI investment focuses on helping customers help themselves.

That’s important, but it’s only part of the picture.

When a customer reaches an affordability assessment, particularly where financial circumstances are more complicated, organisations need their agents to perform at their very best.

The next generation of affordability technology shouldn’t simply aim to replace people. It should help agents become more consistent, more confident and better equipped to have the conversations that only humans can have.

That’s the philosophy behind Inicio.

AI Build for the Agent

Rather than creating another customer self-service tool, Inicio has been designed specifically to support agents during affordability conversations.

As the conversation progresses, Inicio provides structured guidance, helping agents explore a customer’s financial circumstances consistently and thoroughly.

It highlights where information may be incomplete, prompts further exploration when responses appear inconsistent, captures a comprehensive audit trail and removes the need for agents to remember complex processes or navigate lengthy forms.

The technology provides the structure.

The agent provides the empathy, judgement and trust.

Why That Matters

Supporting agents in this way delivers benefits that go far beyond improving individual conversations.

Because every agent follows the same structured guidance, organisations achieve greater consistency across teams. New colleagues become productive more quickly, experienced agents spend less time managing process, and affordability assessments become more robust and easier to evidence.

The result is higher quality conversations, stronger governance, shorter training times and more resilient operations.

These outcomes are becoming increasingly important as affordability expectations continue to evolve and firms look to demonstrate consistent customer outcomes.

A Different View of AI

The financial services industry often talks about AI replacing manual processes.

We believe there’s a bigger opportunity.

As technology continues to remove routine interactions, the conversations that remain become more valuable, more nuanced and more important.

Those conversations deserve exceptional agents.

And exceptional agents deserve exceptional support.

At Inicio, we believe the future of affordability isn’t about choosing between AI and people.

It’s about combining the strengths of both.

Because when the conversation matters most, the agent matters most.

Amani Darr

Amani Darr

Head of Customer Success

As AI and digital self-service transform customer interactions, the role of the human agent is becoming more important, not less. Amani explores how conversational AI can support agents during complex affordability assessments, improving consistency, confidence and customer outcomes while leaving empathy, judgement and trust firmly in human hands.